How to Save for a Luxury Watch Without Giving Up Brunch
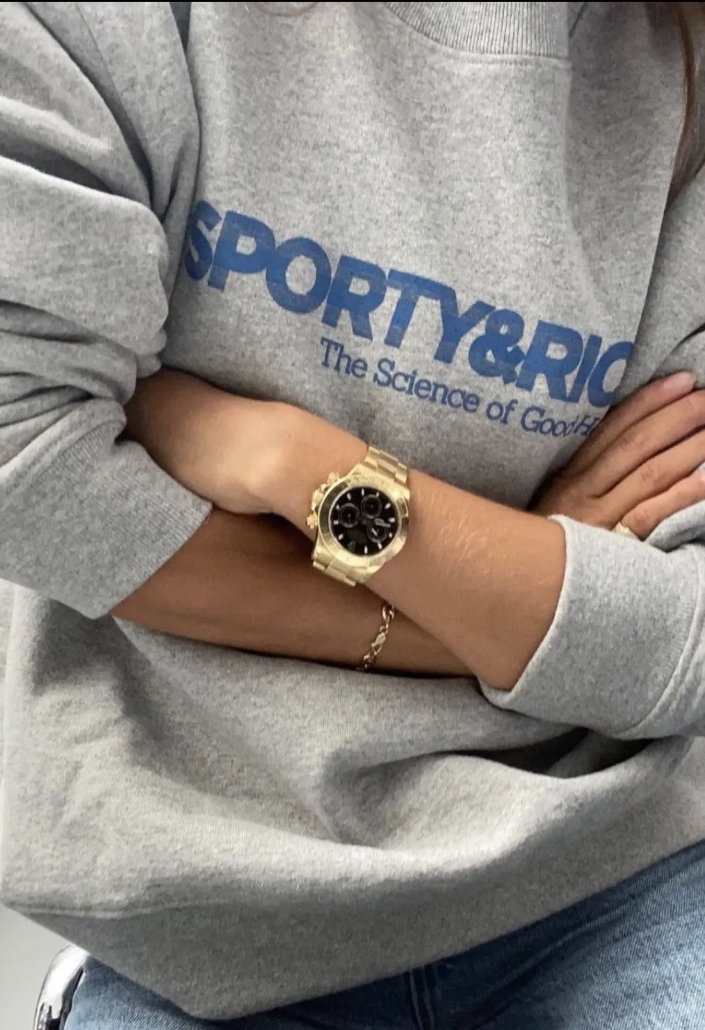
Wanting something expensive while still enjoying your everyday life can feel like a contradiction. Most savings advice treats pleasure as the enemy: cut the coffee, skip the dinners out, and turn down plans with friends until you hit your goal. That sounds sensible on paper, but it rarely holds up in real life, because people who feel deprived usually give up.
Savings goals don’t fall apart because of small treats. They fall apart because the target is vague, the money has no clear job, and the whole plan depends on willpower. A better approach swaps sacrifice for structure. You give every dollar a purpose, including the ones meant for fun, and you set things up so the saving happens without much effort. The steps below walk through how to do that, from working out the real cost to making the purchase.
Start With the Real Price, Not the Sticker Price
A savings plan is only as good as the number it’s aiming for. Many people pick a watch, note the retail price and start saving, only to discover extra costs just as the finish line comes into view.
Count the Costs That Come After the Purchase
A mechanical watch isn’t a one-time expense. Most brands recommend a full service every five to ten years, and that can cost several hundred dollars. Sales tax can also add a sizable amount to a four-figure purchase. Then there’s insurance. A $6,000 watch is worth protecting, and adding it to a renter’s or homeowner’s policy comes with a yearly cost. None of these expenses is huge on its own, but together they can add 10 to 15 percent to the true price.
Decide Between New and Pre-Owned Early
This choice affects your target more than almost anything else. Many models sell on the pre-owned market for well below retail. A few popular ones do the opposite and sell for more than retail because demand is higher than supply. Research the exact model you want before settling on a number. If you’re open to pre-owned, plan to buy from a dealer who authenticates their watches and offers a warranty. You may pay a little more, but it’s cheap protection against an expensive mistake.
Turn the Price Into a Monthly Figure
Once you know the real cost, set a deadline. A $7,200 total over 24 months works out to $300 a month. Over 18 months, it’s $400. Breaking the goal into a monthly amount makes it feel less overwhelming, more like a regular bill than a distant dream. It also shows right away whether your timeline fits your income or needs some adjusting.
Find the Money Without Touching the Brunch Budget
With a monthly target in hand, the next question is where the money will come from. The natural instinct is to cut whatever feels indulgent. Try not to. Brunch is easy to spot, it’s social and it’s genuinely enjoyable, but it’s rarely where your money is quietly slipping away.
Give Fun Its Own Line in the Budget
The best way to protect brunch is to budget for it. Decide what a comfortable month of weekend meals looks like, say $160 for four outings, and treat that as a fixed expense, just like rent. Spending that money isn’t a setback. It’s part of the plan. This one step removes much of the guilt that makes people abandon their savings goals halfway through.
Look for the Spending You Don’t Notice
The money for the watch is usually hiding in expenses you barely think about. Streaming services you forgot you signed up for. A gym membership you use twice a month. Delivery fees that turn a $14 meal into a $24 one. Go through three months of bank and card statements line by line. Most people find $100 to $200 a month in charges they wouldn’t miss, which can cover a third or more of the monthly target without changing a single weekend plan.
Put Unexpected Money to Work
One-off cash is the quickest way to shorten your timeline. A tax refund, a work bonus, cash gifts or a raise can all help you jump ahead. A simple rule keeps it fair: put half toward the watch and keep the other half for yourself. You still enjoy the extra money, and your goal moves forward in bigger steps.
Make the Savings Automatic
Finding the money is only half the job. Holding on to it is the other half. If your plan depends on remembering to move money at the end of the month, a busy week will eventually get in the way.
Use a Separate Account With a Name
Money left in a checking account tends to get spent. Open a savings account just for the watch and give it a name you’ll recognize, even the name of the model. Make sure it’s covered by FDIC deposit insurance, which protects deposits at member banks up to the legal limit. A named account makes the goal feel real and gives you something to check on as it grows.
Schedule Transfers for Payday
Set up the transfer to go out on the same day your paycheck arrives. If the money never sits in your spending account, you won’t miss it. After two or three months, you’ll stop noticing the transfer, and watching the balance grow will keep you motivated.
Let Interest Help, Within Reason
A high-yield savings account won’t pay for the watch, but it will add a little extra on top of what you put in. You can see what a steady monthly deposit might earn over your timeline with the SEC’s compound interest calculator. For a goal that’s about two years away, keep the money in savings rather than the stock market. A market drop just before you plan to buy could erase months of progress.
Why Good Financial Advice Makes the Goal Easier
Everything above works on its own. Still, a luxury purchase doesn’t exist in a vacuum. It competes with rent, debt, retirement and every other goal for a share of the same paycheck, and that’s where good advice becomes valuable.
A solid financial advisor asks the questions many people skip. Do you have an emergency fund? The Consumer Financial Protection Bureau’s guide to building one explains why it makes sense to set aside cash for surprises before saving for other goals. Are you contributing enough to get your full employer retirement match? Do you have credit card debt charging 20 percent or more while your watch fund earns far less? A good advisor helps you tackle these in the right order, so buying the watch doesn’t quietly set back something more important.
Technology has made this kind of guidance much easier to access. Apps that use AI-driven financial planning can scan months of transactions in seconds, flag subscriptions you forgot about and show how adding $50 a month would change the date you can buy.
They can also answer the kind of questions that pop up late at night but don’t justify booking an appointment, such as whether a bonus should go toward debt or savings first. Their biggest strengths are speed and the ability to spot patterns. Something that might take you an afternoon to find, software can catch almost instantly. Still, these tools work best as a starting point. Weigh their suggestions against your own priorities, and take bigger decisions to a qualified professional.
Mistakes That Stretch the Timeline
Even a well-built plan can go off track. Knowing the most common mistakes makes them easier to avoid.
Financing the Watch
Buy-now-pay-later deals and store credit make the watch feel affordable today, but they come with interest or fees and take away the satisfaction of owning it outright. If your plan says 20 months, taking a loan to get the watch in the first month just means paying more for the same thing.
Borrowing From the Fund
A great pair of boots goes on sale, or a weekend trip comes up. Taking “just a little” from the watch fund feels harmless, but it sets you back and makes the account feel optional. If other purchases keep coming up, give them their own savings goal.
Moving the Goalposts
Months of research can easily lead you toward a more expensive model. Upgrading is fine if you decide to do it and adjust your monthly savings or your timeline to match. Letting your target creep upward without changing the plan is how an 18-month goal turns into a three-year one.
Conclusion
Saving for a luxury watch doesn’t mean giving up the small pleasures that make ordinary weeks enjoyable. It takes a realistic price, a clear monthly target, a set budget for fun and a system that moves money before you have a chance to spend it. Good advice, whether from a professional or a well-designed app, helps keep the goal in balance with everything else. With that structure in place, the watch becomes your reward for sticking to the plan, and your brunch reservations can stay right where they are.
xoxo


